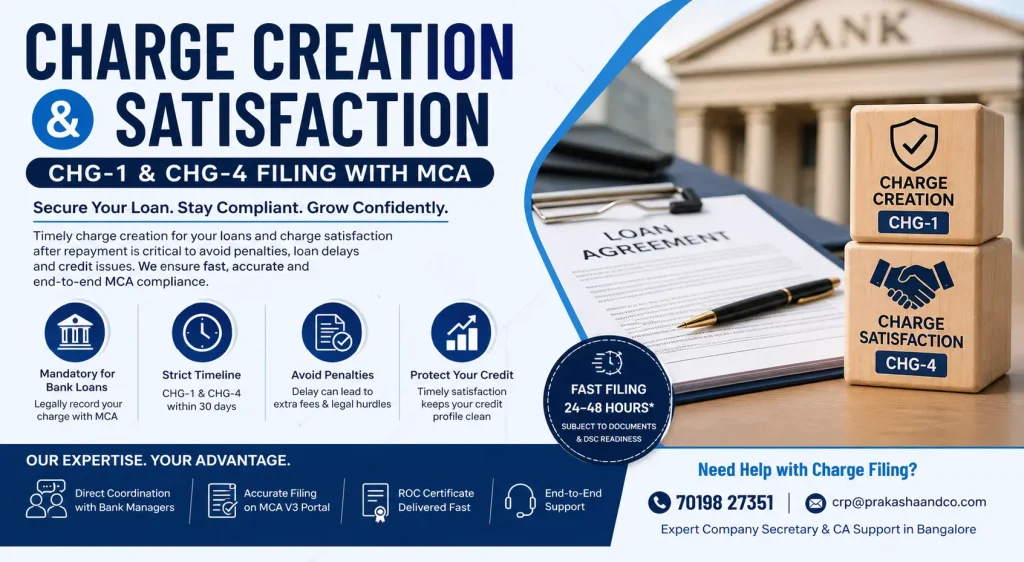
Charge creation is required when a company takes a loan from a bank or financial institution and must be filed with MCA to legally record the security.
Charge Creation & Charge Satisfaction – Critical MCA Filing for Bank Loans
Charge creation is mandatory when a company takes a loan from a bank or financial institution, and charge satisfaction must be filed once the loan is fully repaid.
These filings ensure that your loan is legally recorded on MCA and protect both the lender and the company from future disputes.
🔐 Charge = Digital Mortgage on MCA
A charge is like a public record of your company’s loan:
- ✔ Filed using CHG-1 (Creation / Modification)
- ✔ Closed using CHG-4 (Satisfaction)
👉 If not filed, the bank is treated as unsecured creditor and may stop disbursement.
⚠️ Critical Timeline – Don’t Miss This
- ✔ CHG-1 must be filed within 30 days
- ✔ Banks often require filing within 15 days
- ✔ CHG-4 must be filed within 30 days of loan closure
👉 Delay can block loan disbursement or attract penalties.
💡 Real Problem Faced by Businesses
- ✔ Bank gives documents at last moment
- ✔ DSC of branch manager not coordinated
- ✔ Filing delayed → loan gets stuck
- ✔ After repayment, satisfaction not filed
👉 Many companies face penalties or loan rejection due to this.
📊 Impact on Credit & Future Loans
- ✔ Unsatisfied charge shows as “active loan”
- ✔ Affects credit rating (CIBIL / CRISIL)
- ✔ New loan may be rejected
👉 Even after repayment, your company may appear debt-heavy if CHG-4 is not filed.
🚀 Professional Insight (Value Add)
Filing charge is not just compliance — it directly affects:
- ✔ Loan disbursement speed
- ✔ Bank approval process
- ✔ Company credit profile
👉 Proper coordination between Company, Bank & PCS is required.
Loan disbursement stuck or charge filing pending?
Get 24-hour charge filing support with direct bank coordination.
📞 7019827351 | 📧 crp@prakashaandco.com
Step-by-Step Process – Charge Creation (CHG-1) & Charge Satisfaction (CHG-4)
Charge filing involves coordination between the company, bank and MCA portal. A delay at any stage can impact loan disbursement.
| Step | Action | Form |
|---|---|---|
| 1 | Loan sanction & agreement execution | Bank Stage |
| 2 | Board resolution for borrowing (Sec 180) | Resolution |
| 3 | Preparation of charge details (asset / amount) | Drafting |
| 4 | Digital signature from director & bank manager | DSC Coordination |
| 5 | Filing of charge with ROC | CHG-1 |
| 6 | ROC approval & certificate of charge | Certificate |
| 7 | Loan closure & NOC from bank | Closure |
| 8 | Filing of satisfaction of charge | CHG-4 |
⚠️ Timeline You Cannot Miss
- ✔ CHG-1: Within 30 days (banks expect within 15 days)
- ✔ CHG-4: Within 30 days from loan closure
👉 Delay leads to additional fees and legal complications.
🔐 The “Three-Way DSC Challenge”
Filing CHG-1 requires:
- ✔ Director DSC
- ✔ Bank Manager DSC
- ✔ Professional certification
👉 Delay in any one causes complete filing delay.
🏦 Bank Coordination – Key to Fast Filing
- ✔ Sanction letter received late
- ✔ Hypothecation deed not finalized
- ✔ Bank DSC not ready
👉 Direct coordination with bank manager is required for smooth filing.
📊 Charge Modification (Important Case)
If loan limit increases (e.g. ₹1 Cr → ₹2 Cr):
- ✔ File modification (not new charge)
- ✔ Done through CHG-1
👉 Avoids duplication and legal confusion.
🔗 Related Compliance
Documents Required – Charge Creation (CHG-1) & Satisfaction (CHG-4)
Proper documentation is critical for successful charge filing. Missing or incorrect documents are the main reason for delays.
📂 Documents for CHG-1 (Charge Creation)
- ✔ Loan sanction letter from bank
- ✔ Hypothecation / mortgage agreement
- ✔ Board resolution for borrowing
- ✔ Details of secured assets
- ✔ Bank branch manager details
- ✔ DSC of director & bank officer
📂 Documents for CHG-4 (Charge Satisfaction)
- ✔ Loan closure / NOC letter from bank
- ✔ Final settlement proof
- ✔ DSC of authorized signatory
💡 Practical Tip (Avoid Delay)
- ✔ Request DSC availability from bank early
- ✔ Confirm charge details with bank before filing
- ✔ Keep loan documents scanned & ready
👉 Most delays happen due to last-minute coordination with banks.
📩 Easy Process for Clients
Just share documents via WhatsApp or email.
- ✔ We review & prepare form
- ✔ Coordinate with bank
- ✔ Complete filing end-to-end
Common Mistakes in Charge Filing
- Filing without bank confirmation
- Wrong charge amount
- Missing DSC
- Delay in CHG-4
FAQs – Charge Creation, Delay Cases & Practical Solutions (CHG-1 / CHG-4)
What is charge creation in MCA?
Charge creation is filing of loan security details with ROC using CHG-1 when a company borrows from a bank or financial institution.
What is charge satisfaction?
Charge satisfaction is filed through CHG-4 after full repayment of loan to remove charge from MCA records.
What is the time limit for CHG-1 filing?
It must be filed within 30 days from the date of creation of charge. Banks usually expect filing within 15 days.
What happens if we miss the CHG-1 deadline?
Delay attracts additional fees and may require additional approvals. In some cases, delay may impact loan disbursement.
⚠️ What if MCA does not allow filing due to delay?
If the delay exceeds permissible limit:
- ✔ Application for condonation of delay may be required
- ✔ Additional documentation & justification needed
- ✔ Higher government fees applicable
👉 We assist in handling delayed cases and bringing the charge into compliance.
Bank has prepared CHG-1 but needs CS/CA certification – can you help?
Yes. We provide professional certification for CHG-1 / CHG-4 filing after verification of documents.
If your branch requires quick certification and filing support, you can coordinate directly with our office for fast processing and compliance.
We have repaid loan but not filed CHG-4 – what to do?
You should immediately file satisfaction of charge. Delay will keep the loan active in MCA records and affect credit profile.
Can one loan have multiple charges?
Yes. Depending on security structure, multiple charges or modifications can be filed.
What is the cost for charge filing?
Our professional fees start from ₹1,500 and vary depending on complexity, delay and bank coordination requirements.
How quickly can you complete filing?
Normally within 24–48 hours, subject to availability of bank DSC and documents.
Can loan be disbursed without charge creation?
In most cases, banks require charge creation filing before or immediately after disbursement. Delay may result in hold or compliance issue.
About the Author
Prakasha C R (FCS 11130, COP 15592) is a Company Secretary, Chartered Accountant and Legal Advisor with over 15+ years of experience in MCA compliance, charge filing, loan structuring and corporate advisory.
Our team assists companies, startups and bankers in ensuring complete compliance under Companies Act with practical execution support.
🔗 Related Services
Last Updated: 01 May 2026