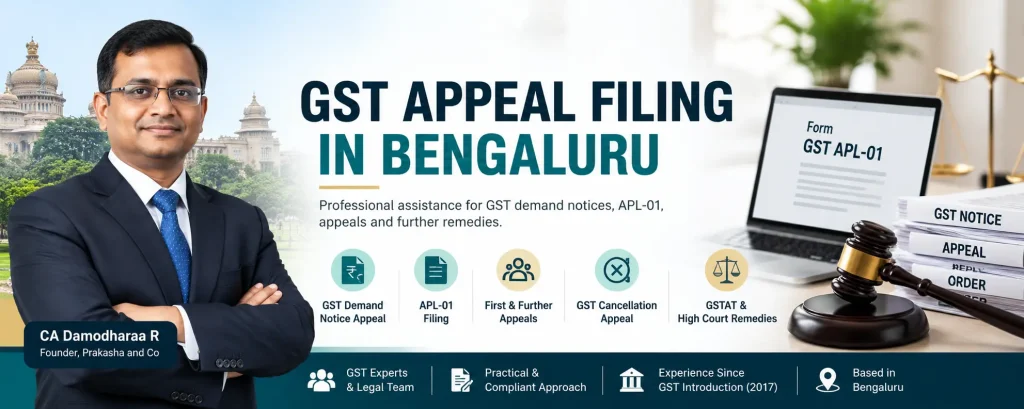
Received a GST Demand? Let’s Review Your Legal Options.
A GST demand, ITC rejection or cancellation order can affect your business cash flow and create recovery pressure. Before paying a disputed amount, have the order examined by an experienced professional.
CA Damodharaa R | 20+ years of professional experience
Prakasha and Co assists businesses with GST appeal filing, Form APL-01, pre-deposit calculations, appellate representation and further legal remedies where available under the law.
How We Can Help With Your GST Appeal
The right remedy depends on the order you received. We review your documents, explain the available options and help you take the next legally appropriate step.
GST Appeal APL-01 Filing
Challenge an eligible adjudication order through a first appeal. We assist with limitation checks, drafting, pre-deposit calculations and online filing.
ITC Disallowance & Tax Demand
We examine ITC records, invoices, return reconciliations and demand calculations to identify grounds that may support your appeal.
GST Cancellation Appeal
If your GST registration has been cancelled, we review the order, reasons for cancellation and the appropriate appeal or restoration remedy.
GSTAT Second Appeal
We assist with eligible second appeals before the GST Appellate Tribunal, including review of the first appellate order and applicable filing requirements.
High Court & Further Remedies
Where legally maintainable, we assess further remedies, including appropriate High Court proceedings and Supreme Court proceedings where the law permits.
Hearing & Legal Representation
We prepare written submissions, organise evidence and assist with representation before the competent appellate authority.
Getting Started Is Simple
You do not need to understand every GST provision before contacting us. Start by sharing the order and its communication date.
Tell us what order you received and when it was communicated.
We assess the deadline, disputed amount and possible legal grounds.
We explain the likely professional fee and applicable pre-deposit.
After engagement, we assist with filing and subsequent representation.
Let’s Discuss Your GST Dispute
Facing a demand, ITC rejection or cancellation order? Share your details for an initial review of the appropriate next steps.
Consultant
CA Damodharaa R
Firm
Prakasha and Co
Office
No. 17/1, 2nd Floor,
Sahakar Nagar,
Bengaluru – 560092, Karnataka
Phone / WhatsApp
+91 70198 27351
Email
prakashaandco@gmail.com
GST Appeal Procedure: Deadline, Payment & Filing
Received an adverse GST order? Three things matter immediately: your appeal deadline, the amount you must deposit, and the documents needed for filing. Our team helps you assess these requirements before proceeding.
Check Your Deadline
We examine the order and communication records to calculate the limitation period and identify any urgency before filing.
Calculate Your Pre-Deposit
We determine the admitted dues, disputed tax and applicable statutory pre-deposit before the appeal is submitted.
Prepare & File APL-01
We prepare the appeal grounds, organise supporting records and assist with online filing and acknowledgement follow-up.
How Much Must You Pay to File a GST Appeal?
For a typical first appeal against a tax demand, Section 107(6) generally requires payment of the admitted dues and a pre-deposit of 10% of the remaining disputed tax, subject to the applicable statutory conditions and limits.
| Particulars | Illustrative Amount |
|---|---|
| Disputed tax | ₹20,00,000 |
| Pre-deposit at 10% | ₹2,00,000 |
| Remaining disputed tax | ₹18,00,000 |
This example assumes that the entire tax amount is disputed and no tax liability is admitted. The actual calculation depends on your order and applicable law.
What If the GST Portal Shows a Payment Error?
A mismatch involving DRC-03, the electronic liability records or pre-deposit payment can delay filing. We help reconcile payment records, identify the issue and document portal errors. A technical grievance does not automatically extend the statutory appeal deadline.
Not Sure How Much You Must Pay?
Send us your GST order and its communication date. We can assess the limitation period, applicable pre-deposit and next steps for your appeal.
WhatsApp Your GST Order Submit Your EnquiryGST Cancellation Appeal & Revocation
Has the GST department cancelled your registration? You may lose the ability to issue valid tax invoices, collect GST as a registered supplier and conduct normal business operations under an active registration. The correct remedy depends on who cancelled the registration, why it was cancelled and when the order was communicated.
Appeal Against GST Cancellation
If the GST officer cancelled your registration and you believe the order is incorrect, you may be able to challenge it before the appropriate appellate authority.
- Review the cancellation order and stated reasons.
- Examine notices, replies and hearing records.
- Prepare grounds supported by documents.
- Check the appeal deadline and applicable requirements.
Revocation of GST Registration Cancellation
Where the law permits, an application for revocation may help restore a registration cancelled by the department. Eligibility and compliance requirements must be checked first.
- Identify the reason for cancellation.
- Review pending returns and applicable tax dues.
- Check the prescribed application period.
- Prepare the application and supporting documents.
These are different legal remedies. Revocation generally concerns restoration of a registration cancelled by the proper officer, subject to the applicable statutory conditions. An appeal challenges an appealable order. The correct route depends on your facts and the law in force.
Documents We Need to Review Your Case
- GST registration certificate and GSTIN.
- Cancellation order and notice, if available.
- Replies already submitted to the department.
- Pending return and tax-payment details.
- Supporting business records and departmental correspondence.
Need Help Restoring Your GST Registration?
CA Damodharaa R at Prakasha and Co assists businesses in Bengaluru with GST cancellation disputes, revocation applications and appeals. Share your order for an initial review of the available remedy.
WhatsApp Your GST Order Submit Your EnquiryGSTAT Second Appeal & High Court Remedies
Has your first GST appeal been rejected, or has the appellate authority upheld a disputed demand? You may have further legal remedies. The appropriate forum depends on the order, the grounds of challenge, statutory deadlines and the applicable provisions.
GST Appellate Tribunal (GSTAT)
Eligible taxpayers can challenge an order of the first appellate authority before the GST Appellate Tribunal. We review the earlier order, identify appealable errors and assist with the applicable filing requirements, pre-deposit and written submissions.
High Court GST Appeal
Where the law permits, a High Court petition or appeal may be considered for jurisdictional errors, violations of natural justice or other legally sustainable grounds. The appropriate remedy depends on the facts and statutory appeal structure.
Supreme Court Proceedings
Further proceedings before the Supreme Court may be available in eligible cases, subject to the governing statutory provisions and constitutional jurisdiction. We help assess the appropriate procedural route and further legal requirements.
How We Help With Further GST Appeals
- Review the first appellate order and earlier submissions.
- Identify possible errors in law, jurisdiction or procedure.
- Examine the applicable limitation period and pre-deposit.
- Prepare appeal papers and supporting legal submissions.
- Coordinate representation and further proceedings as agreed.
Need to Challenge an Unfavourable GST Order?
CA Damodharaa R at Prakasha and Co assists businesses in Bengaluru with GST appeals and further legal remedies, subject to the applicable law and jurisdiction.
Discuss Your GST Appeal Submit Your EnquiryGST First Appeal Rejected? Explore Your Next Legal Remedy
Did your GST appeal fail before the Joint Commissioner (Appeals), Additional Commissioner (Appeals) or another designated first appellate authority?
An unfavourable first appeal order does not necessarily mean that your GST dispute is over. Depending on the order, applicable law and limitation period, a further appeal may be available before the Goods and Services Tax Appellate Tribunal (GSTAT).
At Prakasha and Co, Bengaluru, CA Damodharaa R can review the first appellate order, including cases previously handled by another consultant, and assess the available next steps.
How We Can Assist After an Unsuccessful GST Appeal
- Independent review of the earlier appeal: Examine the order, grounds raised, evidence submitted and reasoning adopted by the appellate authority.
- Identify potential appeal grounds: Assess whether the order raises arguable issues involving GST provisions, ITC eligibility, tax demand, limitation, natural justice, evidence or procedural compliance.
- Review the earlier consultant’s work: Examine available filings and submissions to identify issues that may require further legal analysis. The review does not presume that the earlier consultant made an error.
- Assess a second appeal before GSTAT: Where legally maintainable, evaluate the grounds, limitation, applicable pre-deposit and documentation required for the next appellate stage.
- Prepare the next-stage appeal: Assist with organising the record, formulating grounds and preparing the appeal within the applicable legal framework.
GST DRC-03A: Adjustment of GST Payment Towards a Demand
Have you already paid an amount through Form GST DRC-03 but the payment is not reflected against the relevant demand? Form GST DRC-03A provides a mechanism, subject to applicable conditions, to link an eligible DRC-03 payment with the corresponding demand.
When Is Form GST DRC-03A Relevant?
- A payment intended for a specific GST demand was made through Form GST DRC-03.
- The payment needs to be mapped to the corresponding demand reference or Demand ID.
- The eligible amount may need to be considered while determining the outstanding liability or applicable appeal pre-deposit.
- The taxpayer needs to verify whether the payment and demand qualify for adjustment under the applicable rules and guidance.
How the DRC-03A Process Works
- Review the demand: Identify the relevant order, demand reference and outstanding liability.
- Verify the original payment: Check the DRC-03, payment date, amount, tax heads and supporting challan or receipt.
- Check eligibility: Confirm that the payment and proceedings qualify for adjustment through DRC-03A.
- Complete the applicable adjustment process: Submit the DRC-03A application through the GST portal where available and retain the acknowledgement and supporting records.
- Recheck the demand and appeal requirement: Verify the updated liability records and calculate any remaining amount payable, including the applicable appeal pre-deposit.
GST Appeal Fees & APL-01 Filing Charges
Professional fees depend on the disputed amount, complexity of the case, available records, urgency and scope of representation. The following are indicative fee ranges for planning purposes.
| GST Appeal Service | Indicative Professional Fee | Scope |
|---|---|---|
| GST Appeal Form APL-01 | ₹15,000–₹25,000 | Review of the order, grounds of appeal, supporting documents and filing assistance. |
| GST Appeal Representation | ₹7,500–₹10,000 per hearing | Preparation and representation at a hearing, subject to the agreed scope. |
| Rectification under Section 161 | From ₹5,000 | Review and preparation of a rectification request for an apparent error, where legally available. |
| Unfavourable First Appeal Review | Quoted after review | Review of the first appellate order and assessment of potential further remedies. |
| GSTAT Second Appeal Assistance | Quoted after review | Scope and fee determined after assessing the order, records, grounds and filing requirements. |
| GST DRC-03A Assistance | Quoted after review | Review of the payment, demand reference and applicable adjustment procedure. |
Documents Required for GST Appeal Filing
Provide the documents relevant to your case. Additional records may be required depending on the order, tax period and appellate forum.
Assessment, demand, penalty or cancellation order with annexures.
SCN, DRC-01, DRC-07 and related notices, where applicable.
Replies, written explanations, evidence and hearing records.
Relevant GSTR-1, GSTR-3B, GSTR-9 or GSTR-9C and reconciliations.
Tax invoices, purchase registers, supplier details and other relevant input tax credit evidence.
DRC-03, DRC-03A, challans, payment receipts and pre-deposit evidence.
Electronic credit, cash and liability ledger extracts.
Order communication date, downloads, acknowledgements and error screenshots, if relevant.
GST registration details, GSTIN and applicable authorisation or board resolution.
APL-01, grounds of appeal, annexures, acknowledgements and correspondence from the earlier consultant.
The complete order passed by the Joint Commissioner (Appeals), Additional Commissioner (Appeals) or other competent authority.
Any further appeal already filed, relevant notices and payment or pre-deposit records.
GST Appeal APL-01, DRC-03A & Second Appeal FAQs
1. What is the time limit to file GST Appeal Form APL-01?
2. What is Form GST DRC-03A?
3. Is DRC-03A required if I already paid through DRC-03?
4. Can I appeal to the next level if my first GST appeal is rejected?
5. Can Prakasha and Co review an appeal handled by another consultant?
6. What if the limitation period for my next appeal is approaching?
7. Is a 10% pre-deposit required for a GST appeal?
8. Does filing an appeal automatically stop GST recovery?
9. Can I challenge a GST demand involving disallowed ITC?
10. Can I seek rectification instead of filing a further appeal?
Unfavourable GST Order? Let Us Review Your Next Steps.
Whether you need GST APL-01 filing, DRC-03A payment adjustment, a review of an unsuccessful first appeal or assistance assessing a further appeal, contact CA Damodharaa R at Prakasha and Co. Share the order and relevant records for an assessment of the available options.
Discuss Your GST Case on WhatsApp Email Your GST Appeal EnquiryCA Damodharaa R | 20+ years of experience
No. 17/1, 2nd Floor, Sahakar Nagar, Bengaluru – 560092
Phone/WhatsApp: 7019827351
Email: prakashaandco@gmail.com
Our GST Appeal Process
From reviewing your GST order to filing an appeal, we guide you through each step with clear communication and professional support.
Initial Case Review
Share your GST order, notices and relevant documents. We review the case, appeal deadline and possible legal remedies.
Typical timeframe: 1–3 working days after receiving the essential documents.
Strategy & Documentation
We identify potential grounds, prepare the document checklist, explain the applicable pre-deposit and confirm the professional fee.
Timeframe: Depends on case complexity and document availability.
Appeal Preparation & Filing
After engagement and receipt of the required records, we prepare the appeal, coordinate applicable payment requirements and assist with filing and acknowledgement.
Timeframe: Depends on case readiness and statutory deadlines.
Hearing & Follow-Up
We assist with hearing preparation, submissions and follow-up until the appellate authority passes an order, within the agreed scope.
Timeframe: Depends on the authority’s hearing schedule and case progress.
Need Help with Your GST Appeal?
Contact CA Damodharaa R at Prakasha and Co for a review of your GST order, appeal deadline and next steps.
Discuss Your GST Appeal Email Us
Prakasha and Co | Sahakar Nagar, Bengaluru – 560092
Phone/WhatsApp: 7019827351
GST Appeal FAQs: Demand Notices, APL-01 & Legal Remedies
Received a GST demand notice, facing a large tax demand or lost your first appeal? Find answers to common questions about GST appeals, documentation, professional fees and possible next steps.
1. Received a GST demand notice? What should I do first?
2. My GST demand is very high. Can it be reduced or challenged?
3. My GST first appeal was rejected by the Joint Commissioner. Can you take up the next appeal?
4. Can you review a GST case handled by another CA or consultant?
5. What details and documents should I share for a GST appeal review?
- Your GSTIN and business name.
- The GST notice, show-cause notice or impugned order.
- The date you received or accessed the order.
- Earlier replies, appeal papers and hearing communications.
- Relevant GST returns, ITC records and reconciliations.
- DRC-03 payment proof, DRC-03A details and pre-deposit records, if applicable.
6. How much do GST appeal services cost?
7. How long does GST appeal filing take?
8. A GST officer is pressuring me to pay a disputed demand. What should I do?
9. Can I use Form GST DRC-03A if I already paid through DRC-03?
10. Can GST proceedings be challenged if I was not given a proper hearing?
11. Why choose Prakasha and Co for GST appeal assistance?
12. How long has your team been handling GST matters?
Need Help with a GST Demand or Rejected Appeal?
Send us your GST notice or order for an initial discussion. We can assess the documents, identify the applicable deadline and explain the potential next steps.
Discuss Your GST Case Email Your EnquiryNo. 17/1, 2nd Floor, Sahakar Nagar, Bengaluru – 560092
Phone/WhatsApp: 7019827351
Email: prakashaandco@gmail.com